Monday, August 31, 2009

Macro Indicator Summary

I am impressed with markets' resilience in the face of China's 6.7% sell-off overnight. Aside from Hong-Kong, global equity markets have shrugged-off the new Chinese bear market with a disinterested grunt. Here in Canada, banks are mostly higher on the day despite a 1.5% drop in the index, while the U.S. banking sector continues to consolidate sideways, off just 0.75% today.
4:30pm update: Volume was lower across the board, so institutions are sitting on their hands.

9:30pm update: After-hours volume pushed end-of-day numbers well above yesterday's levels, registering a 'distribution day'.

Note: Please click on any and all charts for a larger image.

The clear losers from the China sell-off are commodities, with oil down $3 to below $70, and copper off 12 cents at 2.83. Oil is at critical support from a trend-line going back to late April (see chart of DBO below), while copper has reversed off important resistance at the 61.8% Fibonacci retracement level of $3.00 (See copper Fibs below).

DBO Oil Fund ETF

Source: Stockcharts.com

Copper Market with Fibonacci Levels

Source: Stockcharts.com

Commodity currencies, like the CAD and AUD sold off substantially earlier in the day but have since rebounded, especially against the Yen. The CAD/USD found support from its 50 day moving average slightly below 90 in the morning, and is likely to test its multi-week trend-line (currently at ~89) before finding further direction.

Canadian Dollar ETF

Source: Stockcharts.com

Canadian Dollar ETF / Japanese Yen ETF Ratio

Souce: Stockcharts.com

We monitor the Asian Dollar Index for macroeconomic strength in that region. The index has been consolidating for several weeks in a pennant formation which is likely to break up or down in the next few days. Given the ADXY's strength in the face of China's panic sell-off overnight, an upside breakout is more likely. On an upward break-out, there is resistance at the previous high (~109) which, if broken, would signal further emerging market strength, led by Asia.

Asian Dollar Index

Source: Bloomberg
Bonds are confirming the bearish story in commodities, with long-term Treasuries rallying to resistance for the second time in 2 days.

20+ Year US Treasury Bond ETF

Source: Stockcharts.com

The 10-year TIPS breakeven rate, a measure of bond traders' future inflation expectations, is testing key support today, suggesting that traders are skeptical of current commodity strength.

10-Year TIPS Breakeven Rate

Source: Bloomberg

10-year yields have also been consolidating in a pennant formation; a break of 3.25% would indicate a major change in the trend of 10-year rates, at which point equity bulls would necessarily be put on the defensive.

10-Year US Bond Yield

Source: Bloomberg

Gold continues to consolidate in its intermediate-term pennant structure forming the right shoulder of what looks like a huge inverse head and shoulders formation. This structure suggests higher prices lie ahead. However, there are two clear resistance levels that must be breached before we can celebrate gold's new up-trend. Using the GLD ETF chart, the first resistance line sits at ~$94.25, with the longer-term line at ~$95.50. These are important levels to watch. A breach of the upper resistance line would suggest a re-test of the previous highs near $99, with potential for a test of it's all-time high of $100.44.

GLD US Gold ETF

Source: Stockcharts

Meanwhile, credit spreads seem impervious to the macro fragility implied by the charts above. CDS spreads in Europe and the U.S. continue to consolidate near their intermediate-term lows.

In conclusion, several important macro indicators are testing important resistance and support levels, but the pennant-shaped consolidation patterns suggest trend-continuation at this time. As such, stock markets are likely to move sideways in the short-term, with the potential for a short-term correction driven by commodity weakness. The most likely intermediate-term direction for stocks is up, with the potential for the S&P to move as high as 1200 before we begin wave 3 down. Should 980 be taken out on the S&P, we would look for a more immediate, steeper decline to ensue.

For longer-term context, I leave you with Doug Short's most recent chart of the Three Mega Bear Markets.


Source: Dshort.com

Sunday, August 23, 2009

The Fallacy of Cash on the Sidelines

Merrill Lynch posted the results of its most recent Survey of Fund Managers for August this morning. The survey covered 204 fund managers in 80 countries who control $554 billion in assets, and the data dispels the myth of excess cash on the sidelines.

Barry Ritholtz at ritholtz.com summarized the findings. Note that U.S. markets peaked in September 2007:

• Cash balances plunge to 3.5%, lowest since July'07;

• Highest equity allocation (34% from 7%) since Oct'07;

• Bond allocation (-28% from -12%) lowest since April'07;

• Tech (28%) is the most favored sector everywhere.

Barry concluded, 'While I keep hearing about cash on the sidelines, the professionals seem to be "All In."'

As an addendum to the Merrill Lynch survey (full release pasted below), please see the attached chart of US commercial paper and Money Market assets. The chart was originally posted by WallStreetExaminer.com using US Federal Reserve data. Annotations in red are my own.


Source: WallStreetExaminer.com
Click image for larger version

Conclusion: Investable Money Market fund assets are no higher than at the peak of markets in September 2007. Retail holdings of MM funds have now retraced to the levels of Sept 2007. The spike in Institutional MM assets from Sept 2007 is exactly equivalent to the drop in CP assets over the same time period, offering compelling evidence that companies have simply moved treasury working capital out of CP and into IMM funds. This is NOT parked investment capital, and is unlikely to find its way into stocks.

Investors appear to be exactly as fully invested as they were in September 2007, at the peak of the bull market. This dovetails nicely with the Merrill survey.

That said, the Primary Dealers are swimming in reserves. Liquidity parked in Securities Open Market Accounts at Primary Dealers is also back at September 2007 levels (See PD Liquidity Chart). If the money-centre banks decided to leverage these reserves into the system, they could single-handedly push stocks, commodities and corporate bonds higher. It remains to be seen whether banks will hold these as reserves against 'Level III' assets on their balance sheets or put it to work speculating.


Source: WallStreetExaminer.com
Click image for larger version

*************************************************************************
http://news.prnewswire.com/DisplayReleaseContent.aspx?ACCT=104&STORY=/www/story/08-19-2009/0005079889&EDATE=
NEW YORK, NY UNITED STATES

Questions over Imbalances in Early Stages of Recovery

NEW YORK and LONDON, Aug. 19 /PRNewswire/ -- Investor optimism about the global economy has soared to its highest level in nearly six years, with portfolio managers putting their cash back into equity markets, according to the Merrill Lynch Survey of Fund Managers for August.

A net 75 percent of survey respondents believe the world economy will strengthen in the coming 12 months, the highest reading since November 2003 and up from 63 percent in July. Confidence about corporate health is at its highest since January 2004. A net 70 percent of the panel respondents expect global corporate profits to rise in the coming year, up from 51 percent last month.

August's survey shows that investors are matching their sentiment with action, by putting cash to work. Average cash balances have fallen to 3.5 percent from 4.7 percent in July, their lowest level since July 2007. Equity allocations have risen sharply month-over-month with a net 34 percent of respondents overweight the asset class, up from a net 7 percent in July. Merrill Lynch's Risk and Liquidity Indicator, a measure of risk appetite, has risen to 41, the highest in two years.

"Strong optimism in August represents a big turnaround from the apocalyptic bearishness of March. And yet with four out of five investors predicting below trend growth for the year ahead, a nagging lack of conviction about the durability of the recovery remains," said Michael Hartnett, chief global equities strategist at Banc of America Securities-Merrill Lynch Research. "The equity rally has been narrowly led by China and tech stocks. We have yet to see investors fully embrace cyclical regions such as Japan or Europe, or Western bank stocks."

Lasting recovery requires greater balance

Global emerging markets, led by China, and technology stocks are the strongest engines behind the early recovery. Investors would rather be overweight emerging markets than any other region, and by some distance. A net 33 percent of the panel prefers to overweight emerging markets while investor consensus is to remain underweight the U.S., the eurozone, the U.K. and Japan.

Technology remains the number one sector, with 28 percent of the global panel overweight the industry. Industrials and Materials lag with global fund managers holding 11 percent and 12 percent overweight positions respectively.

Further behind are Banks. Global fund managers remain concerned about the sector, holding a 10 percent underweight position. In contrast, investors within emerging markets are positive about Banks with a net 17 percent of fund managers in the regional survey overweight bank stocks.

Some of these sectoral and regional imbalances are starting to erode, however. Global fund managers have scaled back their underweight positions in bank stocks from 20 percent in July. Industrials and Materials have recovered from underweight positions one month ago. Emerging markets are less popular than in July when 48 percent of the panel most wanted to overweight the region. And Europe is a lot less unpopular. In July, a net 30 percent of respondents wanted to underweight the eurozone. That figure has dropped to just 2 percent in August.

Improved outlook for Europe, but investors drag their feet

Within Europe, fund managers appear as excited about the outlook as their global colleagues. A net 66 percent of respondents to the regional survey expect the European economy to improve in the coming year, up from a net 34 percent in July.

The net percentage expecting earnings per share to rise nearly trebled, reaching 62 compared with a net 23 percent a month ago. Investors in the region took an overweight position in Basic Resources, a cyclical sector, and radically scaled back their overweight position in Pharmaceuticals, a defensive sector.

In contrast to global respondents, those in Europe have failed to inject new money. "European growth optimism has finally caught up with other regions, but fund managers have yet to fully act on this and cash levels have actually increased and overall sector conviction is near record lows," said Patrik Schowitz, European equity strategist at Banc of America Securities-Merrill Lynch Research.

Survey of Fund Managers

A total of 204 fund managers, managing a total of US$554 billion, participated in the global survey from 7 August to 12 August. A total of 177 managers, managing US$370 billion, participated in the regional surveys. The survey was conducted by Banc of America Securities - Merrill Lynch Research with the help of market research company TNS. Through its international network in more than 50 countries, TNS provides market information services in over 80 countries to national and multi-national organizations. It is ranked as the fourth-largest market information group in the world.
----------------------------------------------------

Saturday, August 22, 2009

Forever Blowing Bubbles

Those tortured souls who have thus far clung faithfully to the rules of capitalism, finance and economics they learned in business school have surely been disillusioned by the markets' most recent break to new highs. Like children who have finally relinquished the corporeal reality of Santa Claus, these poor souls may be searching for new rules and theories to legitimize their discipline. After all, we can't all be technical analysts, can we? Someone has to take the first step, buy the first shares in order to break a stock to new highs and trigger the technical feeding frenzy!

Those looking for new meaning in the markets may have already discovered the refreshing empiricism of behavioral economics to fill the theoretical void left from the now incontrovertible refutation of the efficient markets hypothesis and CAPM. Surely everyone now realizes that the only factors that impact asset prices are liquidity and sentiment. The former is measurable, though definitions vary considerably. Volume, cash on the sidelines, monetary growth and velocity, reserves held at Primary Dealers and foreign capital flows all contribute to a predictive measurement of liquidity. Sentiment is more esoteric, but can still be measured using surveys and studies of actual trader commitments. Of course, sentiment is only really predictive of market direction when it reaches extreme levels; extreme levels of bullish sentiment often signal important market tops (who is left on to buy more stock?), while extreme bearishness often signals market bottoms (who is left to sell stocks?).

James Montier of Societe Generale is perhaps the most widely followed practitioner of behavioral finance (as opposed to researchers and theorists like Thaler, Kahneman, Tversky and Smith). A recent missive of his was particularly interesting, as it described the results of a remarkable experiment in behavioral finance that may have some bearing on the present market environment.

From the report:

"As the US market is now back at fair value [950 at time of writing], I've been pondering what could drive the market higher. Jeremy Grantham provides some answers in his latest missive to clients. He argues that "the greatest monetary and fiscal stimulus by far in US history" coupled with a "super colossal dose of moral hazard" could generate a stock market rally "far in excess of anything justified by…economic fundamentals". This viewpoint receives support from the latest finding from experimental economics. The evidence from this field shows that even amongst the normally well behaved 'experienced' subjects, a very large liquidity shock can reignite a bubble!"

Mr. Montier then goes on to describe the results of an important study involving experimental markets (in which participants trade an equity-like asset against one another in a simulation), which suggests that experience helps to prevent bubbles - but that it takes more than one experience to change behavior. Explains Montier, "The first time people play the game, they create a massive bubble (like the dot.com bubble). The second time people play the game, they create yet another bubble. However, this seems to be driven by overconfidence that this time they will get out before the top. The third time subjects encounter the game, they generally end up with prices close to fundamental value."


To reiterate, experimental results indicate that even subjects who have experienced the euphoria and losses from the creation and eventual implosion of one market bubble will almost always go on to create another bubble under similar conditions. When surveyed after the fact to explain why they made the same mistake a second time, subjects overwhelmingly indicated that they were confident they could get out ahead of the crash. When subjects realized after their second failed attempt that they were unlikely to outsmart the bubble, they finally refused to create a bubble on their third encounter with the game.


Of particular interest in today's environment, the experimenters took the simulation one step further to discover whether, under the right conditions, they could cause the same experienced participants to create yet another bubble. It turns out that all it takes to re-ignite another bubble among experienced game participants is a massive liquidity injection. To wit, "new research by the godfather of experimental economics, Vernon Smith, shows that it is possible to reignite bubbles even amongst the normally staid and well behaved subjects who have played multiple bubble games. The key to this rekindling is massive liquidity creation. In fact, in his experiments Smith doubled the amount of liquidity available."

Why is this relevant to today's market situation? For starters, the Fed has essentially doubled the monetary base from $850 billion to $1.7 trillion in the past 12 months. Keep in mind that, given the leverage in the system ($~2 trillion in money supplied by the Fed supporting $56 trillion of credit), this has the potential to create a liquidity shock of epic proportions.


Source: FRB

However, given the stagnation in the growth of monetary aggregates (M2 and MZM), banks are not currently leveraging these new reserves. In fact, of the $850 billion added to the monetary base by the Fed, $733 billion has been re-deposited at the Fed by the money-centre banks rather than serving as reserves against new credit creation, suggesting that banks are not yet ready to initiate a new credit cycle. I have attached to charts to this email from the St. Louis Fed for illustrative purposes.


Source: FRB

In conclusion, the Fed and other central banks (notably the Bank of China) have certainly done everything in their power to create the elements necessary to catalyze another asset bubble powered by a new wave of credit creation by the money-centre banks. It remains to be seen whether markets will fall for the same trick a third time. Should the Fed succeed, and new bubbles form, investors would be wise to heed the lesson learned by participants in the market simulation cited above, and beware the trap of overconfidence. Not every investor can be quick enough to avoid the inevitable burst - are your tools up to the task?

Thursday, April 23, 2009

The Escherization of Bank Profits

Yep, even more bankster chicanery.

We knew that many of the banks have been taking advantage of the inscrutable fair value accounting rules by channelling reductions in the market values of their outstanding debt through income statements where they show up as earnings. If the value of outstanding liabilities declines while asset values are constant (under the revised fair value accounting rules introduced a few days ago), this can be recognized as an accounting gain.

This practice allows a bank to pad earnings on the basis that the risk implicit in its outstanding credit obligations has increased, likely due to the bank's deteriorating financial position. (All things equal, as interest rate spreads on a bond increase, the price of the bond (or debt) decreases). The mind-bending implication is that, should the bank's financial situation improve, spreads on its outstanding debt will narrow and the bank will have to book a loss.

Now we discover that, not only are the banks playing strange accounting games with the value of their outstanding liabilities, but many of the banks are actually booking profits from credit insurance written against their own debt! You just can't make this stuff up!

Apparently the CDSs are subject to fair value accounting even though they will ultimately mature with no value unless the company defaults on its own debt.

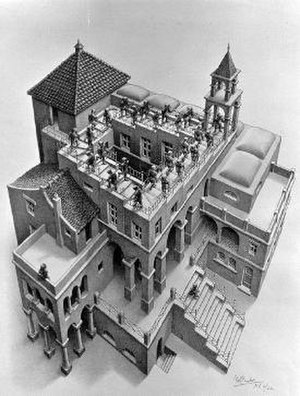
Don't worry if this didn't make any sense on first pass. It is the accounting equivalent of an M. C. Escher drawing.


Source: M.C. Escher via Wikipedia


******************************************************************
From Financial Times' Alphaville Blog:

Banking credit catch-22 in action?
Posted by Tracy Alloway on Apr 22 13:56.

On Monday we wrote about Citi's Q1 gains on credit value adjustments of its CDS.

We're still not sure whether this is an actual CDS position against itself. Citi's Q1statement has the following:

- A net $2.5 billion positive CVA on derivative positions, excluding monolines, mainly due to the widening of Citi's CDS spreads

- A net $30 million positive CVA of Citi's liabilities at fair value option

However, we do note this bit from Morgan Stanley's recently released Q1 results.

In fact, Morgan Stanley would have been profitable this quarter if not for the dramatic improvement in our credit spreads - which is a significant positive development, but had a near-term negative impact on our revenues.

There's a tiny bit more detail in the footnote of on the bank's $1.69bn of Q1 net revenue in Insitutional Securities.

(1) Results for the quarters ended Mar 31, 2008, Dec 31, 2008 and Mar 31, 2009 include positive / (negative) revenues of $1.8 billion, $(5.7) billion and $(1.5) billion, respectively, related to the movement in Morgan Stanley's credit spreads on certain long term debt.

The banking credit catch-22 in action? We wrote this on Monday in relation to Citi.

If the market thinks Citi is doing well, the bank's shares could rise, its CDS could tighten, its CVA gains could well reverse, hitting its earnings, and vice versa. If the market thinks it's doing badly, Citi's CVA gain will increase, but it could still possibly be in need of more capital.

Which today, turns into…

If the market thinks Morgan Stanley is doing well, the bank's shares could rise, its CDS could tighten, its CVA gains could well reverse, hitting its earnings…

This is something of a problem for financials and should serve to highlight the ephemeral nature of certain bank profits in general.

Holding to Account blogger Luca Pacioli (H/T reader JN) for instance, also points us in the direction of 2008 CVA gains from banks including Barclays, RBS, HSBC and Bank of America, totalling at least $13bn. In his words:

Together with Citi, that means approximately $17.9bn will have to be charged back to bank P&Ls. Or put another way - in the last few months, the above banks have reported $17.9bn of profit they probably will never actually realise (this is on top of the general MTM issues on illiquid assets).

Sunday, March 15, 2009

The Looting of America's Coffers

I am increasingly convinced that the looting of fiscal coffers by the international transactional class is one of the great defining issues of our time. I have observed this phenomenon with increasing frustration since the Bear Stearns intervention in early 2008. This type of looting is not new, of course.

We have become a society of looters. The transactional classes feel it is their noble right to perpetuate their status by looting the productive classes. This occurs in three ways:

1. The transfer of tax revenues to entities whose only productive effort is lobbying. This is nothing more than a form of graft and is the enemy of democratic society.

2. The incursion of sovereign debt, which is a tax on the productivity of future generations, in order to offset the natural loss in wealth of the current transactional classes as a result of capitalistic attrition. This looting occurs via 'bail-outs'. Whenever you hear the term 'bail-out' remember that this is a synonym for 'looting'.

3. The continuous creation of fiat money, which dilutes the purchasing power of savers via the hidden tax of inflation. The transactional classes protect themselves from this tax via the ownership of 'assets', the prices of which increase at a rate that exceeds the rate of inflation. It is the fear of asset price deflation that the transactional class fears most of all, and this fear is the motivation for looting.

Importantly, the transactional class is distinguished from the productive class in that the transactional class receives income from capital while the productive class receives income from productivity. Note that those who profit disproportionately from the productivity of others, such as a large fraction of corporate CEOs and other executives are also members of the transactional class, and are by definition 'looters'.

The recent announcement of $165 million in bonuses set aside for payment to executives of AIG provides the perfect example of a transfer of wealth from the productive class (taxpayers) to the transactional class (looters). AIG’s fourth-quarter loss of $61.7 billion was the biggest ever recorded for any U.S. company, and taxpayers are on the hook for several hundred billion dollars in 'bail-outs' to AIG.

**********************************************************************
The Looting of America’s Coffers

By DAVID LEONHARDT

Sixteen years ago, two economists published a research paper with a delightfully simple title: “Looting.”

The economists were George Akerlof, who would later win a Nobel Prize, and Paul Romer, the renowned expert on economic growth. In the paper, they argued that several financial crises in the 1980s, like the Texas real estate bust, had been the result of private investors taking advantage of the government. The investors had borrowed huge amounts of money, made big profits when times were good and then left the government holding the bag for their eventual (and predictable) losses.
In a word, the investors looted. Someone trying to make an honest profit, Professors Akerlof and Romer said, would have operated in a completely different manner. The investors displayed a “total disregard for even the most basic principles of lending,” failing to verify standard information about their borrowers or, in some cases, even to ask for that information.

The investors “acted as if future losses were somebody else’s problem,” the economists wrote. “They were right.”

On Tuesday morning in Washington, Ben Bernanke, the Federal Reserve chairman, gave a speech that read like a sad coda to the “Looting” paper. Because the government is unwilling to let big, interconnected financial firms fail — and because people at those firms knew it — they engaged in what Mr. Bernanke called “excessive risk-taking.” To prevent such problems in the future, he called for tougher regulation.

Now, it would have been nice if the Fed had shown some of this regulatory zeal before the worst financial crisis since the Great Depression. But that day has passed. So people are rightly starting to think about building a new, less vulnerable financial system.

And “Looting” provides a really useful framework. The paper’s message is that the promise of government bailouts isn’t merely one aspect of the problem. It is the core problem.

Promised bailouts mean that anyone lending money to Wall Street — ranging from small-time savers like you and me to the Chinese government — doesn’t have to worry about losing that money. The United States Treasury (which, in the end, is also you and me) will cover the losses. In fact, it has to cover the losses, to prevent a cascade of worldwide losses and panic that would make today’s crisis look tame.

But the knowledge among lenders that their money will ultimately be returned, no matter what, clearly brings a terrible downside. It keeps the lenders from asking tough questions about how their money is being used. Looters — savings and loans and Texas developers in the 1980s; the American International Group, Citigroup, Fannie Mae and the rest in this decade — can then act as if their future losses are indeed somebody else’s problem.

Do you remember the mea culpa that Alan Greenspan, Mr. Bernanke’s predecessor, delivered on Capitol Hill last fall? He said that he was “in a state of shocked disbelief” that “the self-interest” of Wall Street bankers hadn’t prevented this mess.

He shouldn’t have been. The looting theory explains why his laissez-faire theory didn’t hold up. The bankers were acting in their self-interest, after all.

The term that’s used to describe this general problem, of course, is moral hazard. When people are protected from the consequences of risky behavior, they behave in a pretty risky fashion. Bankers can make long-shot investments, knowing that they will keep the profits if they succeed, while the taxpayers will cover the losses.

This form of moral hazard — when profits are privatized and losses are socialized — certainly played a role in creating the current mess. But when I spoke with Mr. Romer on Tuesday, he was careful to make a distinction between classic moral hazard and looting. It’s an important distinction.

With moral hazard, bankers are making real wagers. If those wagers pay off, the government has no role in the transaction. With looting, the government’s involvement is crucial to the whole enterprise.

Think about the so-called liars’ loans from recent years: like those Texas real estate loans from the 1980s, they never had a chance of paying off. Sure, they would deliver big profits for a while, so long as the bubble kept inflating. But when they inevitably imploded, the losses would overwhelm the gains. As Gretchen Morgenson has reported, Merrill Lynch’s losses from the last two years wiped out its profits from the previous decade.

What happened? Banks borrowed money from lenders around the world. The bankers then kept a big chunk of that money for themselves, calling it “management fees” or “performance bonuses.” Once the investments were exposed as hopeless, the lenders — ordinary savers, foreign countries, other banks, you name it — were repaid with government bailouts.

In effect, the bankers had siphoned off this bailout money in advance, years before the government had spent it.

I understand this chain of events sounds a bit like a conspiracy. And in some cases, it surely was. Some A.I.G. employees, to take one example, had to have understood what their credit derivative division in London was doing. But more innocent optimism probably played a role, too. The human mind has a tremendous ability to rationalize, and the possibility of making millions of dollars invites some hard-core rationalization.

Either way, the bottom line is the same: given an incentive to loot, Wall Street did so. “If you think of the financial system as a whole,” Mr. Romer said, “it actually has an incentive to trigger the rare occasions in which tens or hundreds of billions of dollars come flowing out of the Treasury.”

Unfortunately, we can’t very well stop the flow of that money now. The bankers have already walked away with their profits (though many more of them deserve a subpoena to a Congressional hearing room). Allowing A.I.G. to collapse, out of spite, could cause a financial shock bigger than the one that followed the collapse of Lehman Brothers. Modern economies can’t function without credit, which means the financial system needs to be bailed out.

But the future also requires the kind of overhaul that Mr. Bernanke has begun to sketch out. Firms will have to be monitored much more seriously than they were during the Greenspan era. They can’t be allowed to shop around for the regulatory agency that least understands what they’re doing. The biggest Wall Street paydays should be held in escrow until it’s clear they weren’t based on fictional profits.

Above all, as Mr. Romer says, the federal government needs the power and the will to take over a firm as soon as its potential losses exceed its assets. Anything short of that is an invitation to loot.

Mr. Bernanke actually took a step in this direction on Tuesday. He said the government “needs improved tools to allow the orderly resolution of a systemically important nonbank financial firm.” In layman’s terms, he was asking for a clearer legal path to nationalization.

At a time like this, when trust in financial markets is so scant, it may be hard to imagine that looting will ever be a problem again. But it will be. If we don’t get rid of the incentive to loot, the only question is what form the next round of looting will take.

Mr. Akerlof and Mr. Romer finished writing their paper in the early 1990s, when the economy was still suffering a hangover from the excesses of the 1980s. But Mr. Akerlof told Mr. Romer — a skeptical Mr. Romer, as he acknowledged with a laugh on Tuesday — that the next candidate for looting already seemed to be taking shape.

It was an obscure little market called credit derivatives.

Monday, December 22, 2008

Corporate Bond Opportunities

Barrons interviewed Rob Arnott for this weekend's edition.

From Wikipedia:

Robert D. Arnott (born 1954) is an American entrepreneur, investor, editor and writer who focuses on articles about quantitative investing. He edited the CFA Institute's Financial Analysts Journal, as well as three other books on equity and asset allocation management.[1]

Arnott has also served as a Visiting Professor of Finance at the UCLA Anderson School of Management, on the editorial board of the Journal of Portfolio Management, the product advisory board of the Chicago Mercantile Exchange, and the Chicago Board Options Exchange.[1] He previously served as Chairman of First Quadrant, LP, as global equity strategist at Salomon (now Salomon Smith Barney), president of TSA Capital ManagementTSA/Analytic), and as vice president at the Boston Company. He graduated from the University of California at Santa Barbara in 1977.

Rob has been bearish for several years on both bonds and stocks, but he is starting to see some genuine value in risky assets. In particular, Rob expressed enthusiasm for locally priced emerging market bonds, emerging market stocks, and corporate bonds.

Some excerpts:
------------------------------------------------------------------
What's your view now?

... [T]his is the richest environment of low-hanging fruit I've seen in my career. And you would have to go back to 1973, 1974 or even, in some markets, to the Great Depression to find markets priced as attractively as now. This is not a time to be hunkering down in the safety and comfort of the Treasury curve. There are tremendous opportunities right now. It is so tempting in a bear market to focus on the glass being half-empty and on how much has been lost. But the glass being half full side is largely ignored.

What kind of an asset-allocation mix makes sense to you?

First of all, most investors think that putting some money in growth stocks, some money in value stocks and some money in international stocks is a well-diversified portfolio. It's not. Diversification means taking on risk in markets that are uncorrelated and that can go up when other markets go down. So a well-diversified portfolio should look at multiple sources of risk, not just in stocks.

Where do you see opportunities?

A year from now, investors in convertible bonds are likely to be very pleased with what they [see] in terms of prices and yields. The same holds for emerging-market debt denominated in the local currency, which I prefer to dollar-denominated debt. You get a premium yield for emerging-market debt and an additional premium for investing in the local currency. Tacitly, that's a dollar bet, but I don't see how the dollar can do well on a long-term basis when we have indebtedness that is eight times our national income. Imagine an individual going to a bank and saying, "I owe eight times my income and I would like to borrow more." The reaction would be immediate and drastic: "Give us your credit cards; we will slice them up." But as a nation we still have our credit cards, and we are still using them aggressively.

You don't sound like you are sold on stocks, Rob, even after this huge selloff.

The problem I have with stocks -- and it is a very simple problem -- is that while stocks are nicely priced, they aren't attractively priced relative to their own bonds. The savagery of September, October and November was more drastic for bonds than it was for stocks. A 40% drop in stocks is big. A 20% to 30% drop in major categories of bonds is immense. So the take-no-prisoners market actually widened the opportunities on the bond side even more than on the stock side.

Investment-grade corporate bonds are a vivid example of that. The yield spreads over stocks is averaging about six [percentage points] right now. If you can get a 3.5% yield on stocks and 9.5% on the same company's bonds, which is going to give you the higher return? The stocks will, if they show earnings and dividend growth faster than 6% -- but historically that's a stretch. So the bonds have been savaged worse than the stocks have, and actually represent the most interesting opportunity.

So you are talking about investment-grade bonds?

Yes, investment-grade bonds. But for bonds below investment grade, the spreads are quite extraordinary. By the end of November, spreads had widened out to nearly 20 percentage points above Treasuries and also above the corresponding stock yields. Suppose 40% of those bonds go bust next year. And suppose that you get 50 cents on the dollar back on the bonds that go bust. By that point, you have lost your spread of 20 percentage points.

But such a scenario has to happen every year, until the high-yield bonds mature, in order to merely match Treasury returns. A 40% default rate every year for several years would be truly without precedent. So I view 2009 as an "ABT" year -- Anything but Treasuries. The less you hold in Treasuries, the better you are likely to do.

---------------------------------------------------------------

Given Rob's views on corporate and emerging market bonds, and his bearish call on Treasuries, I examined the performance of these markets relative to Treasuries of equivalent duration. I used the iShares fixed income ETFs as investable proxies for these bond market sectors as follows (data as of Friday close):


iShares Barclays 7-10 Yr Treasury Bond Fund (IEF: Effective Duration = 7.00)
iShares iBoxx $ Investment Grade Corporate Bond Fund (LQD: ED = 7.21)
iShares JPMorgan USD Emerging Markets Bond Fund (EMB: ED = 6.67)
iShares iBoxx $ High Yield Corporate Bond Fund (HYG: ED = 6.67)

By utilizing the 7-10 Yr Treasury Bond ETF one can effectively neutralize interest rate risk against the other funds, as the funds all have an effective duration at or near 7. This allows the analysis to focus exclusively on spreads to Treasuries.

Chart 1. Emerging Market Bonds vs Treasuries (Cash yield spread = 590 bps)

Source: Stockcharts.com

Chart 2. High Grade Bonds versus Treasuries (Cash yield spread = 417 bps)

Source: Stockcharts.com

Chart 3. High Yield Bonds versus Treasuries (Cash yield spread = 1504 bps)

Source: Stockcharts.com

Bonds are effectively pricing in the Depression scenario; in order for Treasury yields to continue to decline, and spreads to continue to widen from these levels, the perception of default risk would have to increase beyond the levels of defaults and recoveries actually experienced in either the 30s, the 70s or the 80s by a substantial margin.

Although this is a risk, I view it as a small risk that is easily hedged against this trade by utilizing far out of the money put options on the S&P 500 and/or the emerging markets stock ETF (EEM). Even incorporating the premiums for the purchase of these options, the trade still represents a significant positive carry and a high reward to risk ratio.

Thus I envision a short Treasury ETF / long credit and emerging market bonds ETF trade to focus on the propensity of yield spreads over Treasuries to narrow over the coming weeks and months. This trade has effectively no interest rate risk as the durations of the ETFs in question all approximate 7.

Sunday, December 21, 2008

Prudent Capitalism - China Style


China is behaving in truly Keynesian fashion by cleaning up bad debts on bank balance sheets and demanding prudence and risk management during boom times while forcing banks to expand their balance sheets aggressively during more challenging times in order to move funds into the economy.

Though the author of the article below takes the view that China’s actions within the banking system are inappropriate, I would assert that it is exactly this mechanism for moving funds into the economy that European and North American economies are lacking.

It is also why China is likely to lead us out of this global slump. Chinese shares have been demonstrating consistent relative strength since 
mid-October. Shares in Shanghai and equivalent H-Shares in Hong Kong are making higher highs and higher lows, and they are holding above both short- and longer-term moving averages.


Singapore, Hong Kong and Taiwan appear poised to break out to the upside on the back of the strength in Chinese shares. Brazil and South Africa also look strong and, with both the reais and the rand looking to join the Euro in a surge against the dollar, you may receive a double whammy on the ETFs.

Please see the following story from Dow Jones News.
---------------------------------------------------------------------

Chinese Banks' Great Leap Backward

Around the world, the banks we see today are very different from their former selves of just a few months ago. The transformation has been most pronounced in the U.S. and Europe, where a combination of mergers and government involvement have reshaped the financial sector. But change is afoot elsewhere as well, and it isn't always positive. In particular, Chinese banks are currently under enormous pressure to change their business practices in ways that represent a serious step backward.


A year ago, many of us were ready to be impressed with China's banking system. To be sure, banks were still mainly state-owned, and the Chinese Communist Party continued to be omnipresent. However, the average bank managers were extremely risk conscious, and regulators from the China Banking Regulatory Commission (CBRC) swooped down on bank branches conducting surprise inspections every so often. Bankers were extremely hesitant to make uncollateralized loans to any firm except for the largest corporations.

This was an enormous change from just 10 years ago, when bankers doled out large sums at the slightest urging of the local governments and when banks were considered the "second treasury" by central policy makers. At that time, the nonperforming loan ratio was estimated to be nearly half of all loans outstanding. By January 2008, the official NPL ratio was less than 6%. This transformation wasn't cheap or easy -- it required hundreds of billions of dollars from the government to buy bad loans off bank balance sheets and recapitalize the institutions, and also the participation of Western "strategic partners" brought in to lend their expertise in best practices.

However, risk-prevention institutions built up over the past decade are now under enormous pressure to forgo prudence in the interest of maintaining economic growth. There have been two triggers for this. First, the global recession caused a plunge in demand for Chinese goods -- in November, Chinese exports fell for the first time in nearly a decade. At the same time, the property market continues to shrink in many major Chinese cities.

Anticipating a declining economy, in November the central government announced a four trillion yuan ($586 billion) stimulus package to be carried out in the next two years. At the same time, the National Development and Reform Commission was ordered to approve fixed asset investment worth 100 billion yuan before the end of the year. As of mid-December, much of the money has been doled out. This forceful injection of funds into the economy will be the dominant method of generating growth in the next two years.
---
Banks are trapped in the middle, because they will finance much of the stimulus package. Of the four trillion yuan stimulus, only about a quarter will be financed by the government's central budget. At a time when local governments are strapped for cash due to falling land prices (land sales are a common form of municipal cash-raising), banks are expected to finance much of the remaining three trillion yuan in the package. This isn't a matter of choice. Most banks must follow the government's lead because senior bankers are appointed by the Party.

It gets worse. Local governments have announced a further 20 trillion yuan in investment to "supplement" the central package. Assuming both Beijing and the local governments stick to these spending targets, banks will be under enormous pressure to finance trillions in state-sponsored projects in the next two years. With so much money to push out the door, risk management will almost inevitably take a back seat. Banks that had made enormous strides toward global best practices were compelled by central pressure to greatly boost credit in the last two months of this year.
Prudence is not completely out the window yet because of continuation of CBRC monitoring, but risk management is increasingly a second priority. The CBRC has sent subtle signals to banks to not worry about profit too much and to exclude more risky loans to small- and medium enterprises from their main balance sheets.

Partly as a result, banks are increasingly compromising between risk prevention and political pressure by boosting lending through bill financing instead of writing outright loans. In theory this limits risks because bill financing tends to be short-term and can be easily transferred to another bank. Of the 477 billion yuan of new loans made in November, half were in bill financing. The rise of bill financing may increase systemic risks in the future because banks tend to be less careful when they discount these bills due to their transferability. Loans, on the other hand, are stuck on banks' balance sheets.

Meanwhile, if the economy worsens in the first quarter the government may be tempted to abandon prudent regulation altogether. Beijing could order the CBRC to disregard risk targets or even abolish the CBRC. This would plunge China back into the old days when the only risks that bankers faced were political ones.

Without a global financial crisis, the global financial community might have criticized such a giant step back toward the planned economy. The criticism might have at least triggered some debate in China. However, with the rest of the world suffering a severe credit crunch that has seen free-market governments bailing out their own financial institutions, there are few people left who can credibly criticize China's actions.
Western central banks have conducted operations that once were monopolized by the Chinese central bank and drew scoffs and snorts from the global banking community. For example, the People's Bank of China, the central bank, used to conduct "relending" operations to inject funds into distressed banks to pay creditors or to write off distressed assets. Now, the Federal Reserve is doing the same by buying or accepting as collateral questionable assets from banks.

In any event, everyone is too preoccupied with their own losses to comment on Chinese policies. Which is a problem, not least for China itself. With enormous political pressure from the central government to pump money into the economy and silence from the rest of the world, much of the work in the past decade is being undone.